🔥 TRENDING452 people are currently reading about the Upper Assam Flood Relief efforts⚡ BREAKINGNew IT hub in Guwahati expected to generate 10,000+ jobs by next year🔥 TRENDING452 people are currently reading about the Upper Assam Flood Relief efforts⚡ BREAKINGNew IT hub in Guwahati expected to generate 10,000+ jobs by next year
ETMarkets Smart Talk | How to invest ₹1 crore in bonds for 3 years: Vineet Agarwal’s playbook | The Local News
75%, investors still have an opportunity to lock in attractive fixed-income yields, even though the biggest gains from the recent rate-cut cycle may be behind us. For investors with a three-year horizon, the focus now shifts from chasing capital gains to earning steady carry while managing credit, liquidity and reinvestment risks.
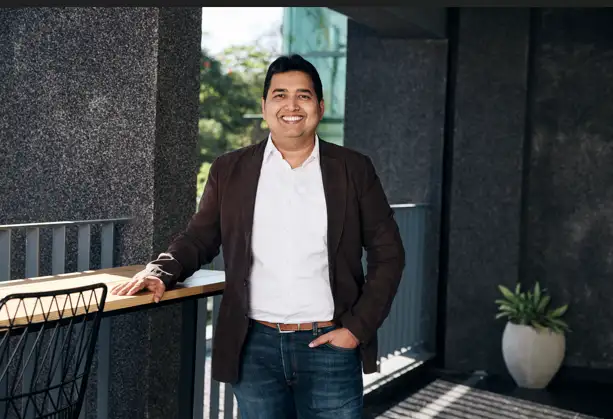
So, how should an investor deploy ₹1 crore in bonds today? Vineet Agarwal, Co-founder, Jiraaf, suggests a diversified and staggered approach, with G-Secs and SDLs forming the safety core, AAA corporate bonds adding yield, selective credit opportunities providing incremental returns, and T-bills or money-market instruments offering liquidity.
German finance ministry links high borrowing costs to security overhaulGermany's borrowing costs have surged to their highest level in fifteen years, influenced by increased security threats following Russia's invasion of Ukraine. The Finance Ministry emphasizes the necessity for substantial investments in defense and security.
Meanwhile, bond yields in other leading Western nations have also risen sharply this week, complicating fiscal policies and raising borrowing costs for both businesses and consumers. He also recommends laddering maturities across one, two and three years rather than putting the entire corpus into a single maturity.
In an interaction with Kshitij Anand of ETMarkets, Agarwal explains how investors can construct a ₹1 crore fixed-income portfolio, whether they should lock in yields now or wait for higher rates, and why selective credit exposure could enhance returns without taking excessive risk. Edited Excerpts –Q) What is your take on the MPC policy meeting outcome?
Do you see interest rates going higher or lower in 2026? 25% with a neutral stance is prudent.
9%. This limits the urgency for further easing.
75%, already on the higher side relative to the policy rate and about 29 bps higher than a year ago. Our base case is therefore a prolonged pause, with a mild downward bias over the medium term if inflation moderates.
However, oil prices, food inflation and global yields could keep bond yields elevated in the near term. 25%, are we still in an environment where investors can lock in attractive yields, or has the best part of the rate cycle already passed?
A) Yes, investors still have a meaningful opportunity to lock in yields. While the strongest capital-gain opportunity from the 125-bps rate-cut cycle may be behind us, the carry opportunity remains attractive.
25% repo rate. More importantly, spreads between the 10-year government benchmark and AAA corporate bonds are currently around 50 to 140 bps, depending on issuer and structure.
For investors with a two-to-four-year horizon, this is a good environment to progressively lock in yields rather than wait exclusively for another rate cycle. Q) Is it better to lock in a 7% yield on a high-quality bond today or wait for potentially higher yields if inflation or oil prices push rates up?
A) I would avoid making this an all-or-nothing decision. 75% and AAA corporate spreads at roughly 50 to 140 bps, investors have access to meaningful yields today.
At the same time, RBI has highlighted risks from food, fuel and global commodity prices, so some upward volatility in yields cannot be ruled out. A better strategy is staggered deployment.
For example, an investor could deploy 50% today, another 25% over the next few months, and retain 25% to take advantage of any rise in yields. This allows investors to lock in current rates while retaining flexibility if inflation or oil pushes yields higher.
Read more: ETMarkets Smart Talk | Nifty enters ‘very attractive’ zone as earnings improve: Union AMC’s Sanjay BembalkarQ) If you had ₹1 crore to deploy in fixed income today with a three-year horizon, how would you construct the portfolio? A) For a three-year horizon, I would prioritize predictability, diversification and liquidity.
An illustrative ₹1 crore portfolio could have ₹25 lakh in G-Secs or SDLs, ₹40 lakh in AAA corporate bonds, ₹20 lakh in selectively chosen AA or other credit opportunities, and ₹15 lakh in T-bills or money-market instruments. The portfolio should also be laddered across roughly 1-year, 2-year and 3-year maturities, rather than concentrating the entire ₹1 crore at one maturity.
Current market levels make this particularly interesting. 75%, while AAA spreads of approximately 50 to 140 bps provide an opportunity to enhance portfolio yield without moving excessively down the credit curve.
The objective should be to lock in attractive carry while keeping credit and reinvestment risks diversified. Q) How should investors divide their fixed-income allocation between government bonds, AAA corporate bonds, credit opportunities and money-market instruments?
A) For a moderate-risk investor, a reasonable starting point could be 25% to 30% in government securities, 35% to 40% in AAA corporate bonds, 15% to 20% in selectively chosen credit opportunities, and 15% to 20% in money-market instruments. The current market makes the government and AAA portions particularly attractive.
75%, while AAA corporate bonds can offer spreads of approximately 50 to 140 bps over the government benchmark. Credit opportunities can provide incremental yield, but they should remain diversified across issuers and sectors.
Money-market exposure provides liquidity and optionality. The broad principle is simple: use sovereign and AAA securities as the portfolio core, and take additional credit risk selectively rather than chasing the highest available yield.
Q) Do you think a bond fund makes more sense than buying individual bonds, and when does direct bond ownership have an advantage? A) Both serve different investor needs.
Bond funds offer professional management and broad diversification, which can be useful for investors who do not want to evaluate individual issuers or actively manage maturities. Direct bonds have an advantage when the investor has a clearly defined two-to-five-year goal and wants greater visibility over coupons, maturity dates and expected cash flows.
An investor can, for example, build a ladder across 12, 24 and 36 months and align maturities with specific financial requirements. Direct ownership is also particularly relevant today because investors can selectively lock in prevailing yields.
75% and AAA corporate spreads of roughly 50 to 140 bps, there are opportunities to construct diversified fixed-income portfolios with attractive carry. Q) How important is tax efficiency when comparing FDs, bonds, debt mutual funds and government securities?
A) Tax efficiency can materially change the return an investor actually earns. 25% before cess for an investor in the 30% tax bracket.
FD interest and bond coupon income are generally taxed at the investor’s applicable slab rate. Capital gains treatment, however, varies by instrument and holding period.
5%, subject to applicable tax provisions. Debt mutual funds and certain other debt instruments can have different treatment.
Therefore, investors should compare post-tax yield, liquidity and credit risk, rather than simply choosing the product with the highest advertised interest rate. Read more: Nifty outlook: Further dips possible before a move towards 25,100, says Anand JamesQ) What is the biggest misconception about bonds in India today, that they are boring, low-return investments?
A) The biggest misconception is that bonds automatically mean low returns. 75%, while AAA corporate bonds can offer an additional 50 to 140 bps depending on the issuer and structure.
15% range, without necessarily taking the level of risk associated with equities or lower-rated credit. More importantly, bonds play a different role from equities.
They can provide contractual cash flows, portfolio stability and maturity visibility, subject to the issuer meeting its obligations. So, being “boring” is actually part of their appeal.
When equities are volatile, having 20% to 40% of a portfolio generating relatively predictable fixed-income cash flows can significantly improve portfolio balance.
US Defense Secretary Pete Hegseth met with Israeli Prime Minister Benjamin Netanyahu during an unannounced visit to Israel on Monday, Axios reported, citing two...