🔥 TRENDING452 people are currently reading about the Upper Assam Flood Relief efforts⚡ BREAKINGNew IT hub in Guwahati expected to generate 10,000+ jobs by next year🔥 TRENDING452 people are currently reading about the Upper Assam Flood Relief efforts⚡ BREAKINGNew IT hub in Guwahati expected to generate 10,000+ jobs by next year
ETMarkets Smart Talk | AI, defence, power: Investors need to be selective as valuations turn expensive, says Aditya Khemani | The Local News
India’s mid and smallcap rally is showing no signs of losing steam, with investors continuing to chase themes such as artificial intelligence, defence, power, data centres and manufacturing. But beneath the headline gains, the market is becoming increasingly polarised, with valuations in several new-age and emerging segments turning expensive.
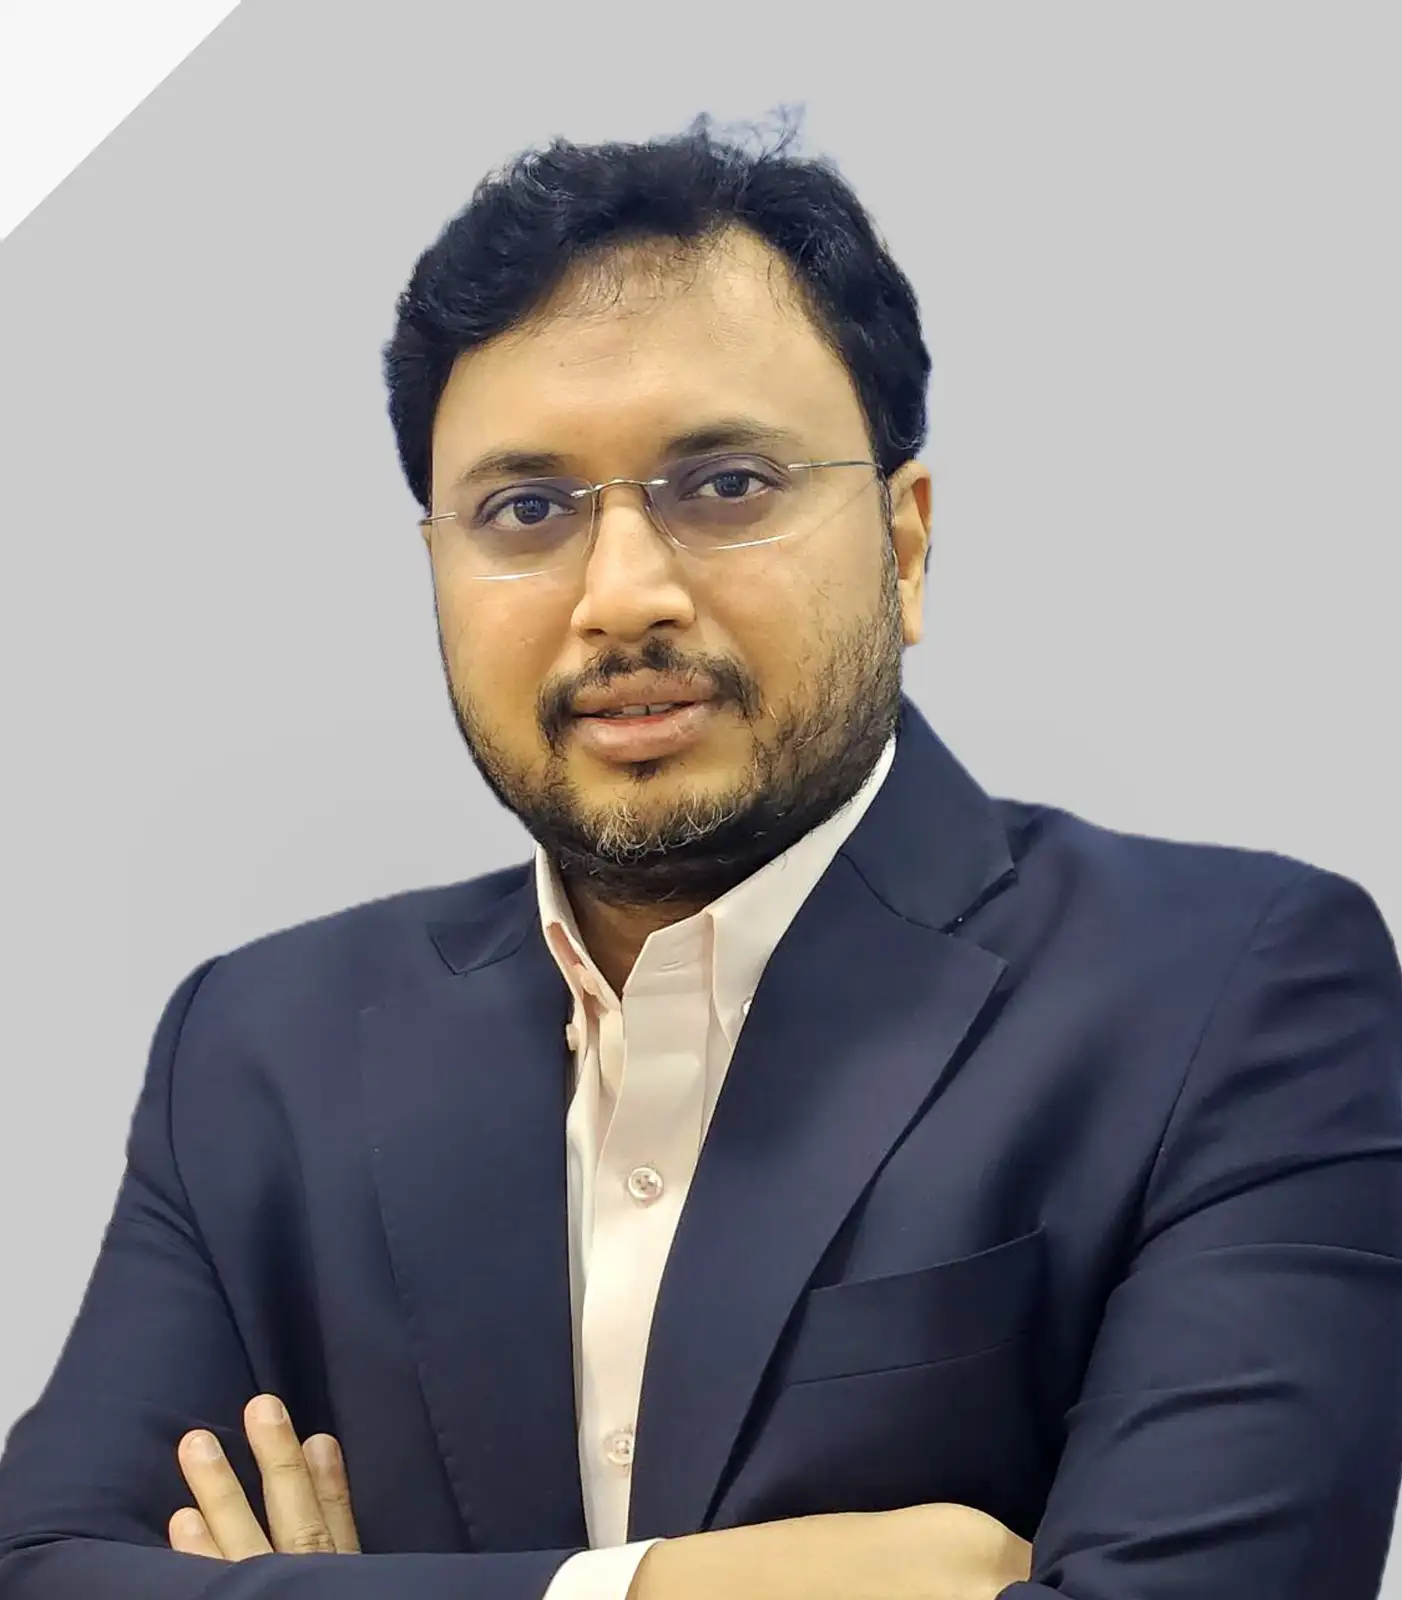
Aditya Khemani, Head of Equities at Invesco Mutual Fund, believes investors need to be particularly selective at this stage. He cautions against confusing strong earnings momentum with business quality, especially when red flags such as weak cash flows or stretched valuations are overlooked.
While India’s growing domestic liquidity provides a cushion against sustained FII selling, Khemani says investors should remain focused on fundamentals, reasonable valuations and the long-term economics of businesses rather than simply following the latest market narrative. In an interaction with Kshitij Anand of ETMarkets, Khemani also discusses the outlook for mid and smallcaps, the AI and defence trade, the impact of higher US yields, and why valuation discipline could become increasingly important for investors.
Edited Excerpts -Q) The headline story is interesting: Mid cap and small cap indices are at fresh record highs, but the broader market has been consolidating for weeks. Are we looking at a healthy rotation beneath the surface or growing complacency?
A) One of the most visible signs of a strong equity market is healthy sector rotation, where market performance is not driven by just a handful of sectors or stocks. Such rotation typically leads to broader participation and more sustainable, long-lasting market gains.
However, over the last six months, the market has increasingly differentiated between the traditional and emerging segments within many sectors, creating a significant gap in performance between the two. Traditional sectors such as consumer staples, banking, and IT have largely underperformed, while emerging areas such as fintech, consumer technology, and segments of the AI value chain, including semiconductors and data centres, have delivered strong returns.
What is particularly notable is the lack of rotation between these two segments. Traditional sectors have continued to lag, while newer-age themes have remained market favourites.
As a result, valuations have become increasingly stretched in certain pockets, driven by strong narratives and earnings momentum. Therefore, I would say that, on an aggregate basis, there are signs of growing complacency in some parts of the broader market.
Importantly, this is not unique to India. Similar trends can be observed globally, where investors are increasingly gravitating towards select themes and growth narratives, resulting in significant valuation divergence across sectors.
Read more: $100 crude is an irritant, not a deal-breaker for India: Harsh Gupta MadhusudanQ) The biggest risk with record highs is that investors confuse momentum with quality. Are we seeing that happen again in parts of the mid and smallcap universe?
A) Over shorter periods, earnings momentum tends to be a significant driver of stock performance. When earnings growth is strong, investors often overlook red flags such as weak cash flows, frequent changes in management, repeated capital raising, and other underlying quality concerns.
In such phases, the market can become overly focused on the profit and loss statement while paying insufficient attention to balance sheet strength. However, when earnings momentum begins to weaken or the narrative turns adverse, investors often realise that they may have mistaken earnings momentum for business quality.
We are seeing some instances of this in certain pockets of the broader market today. That said, I would not characterize this as a widespread phenomenon.
Nevertheless, in a market environment like this, investors need to be particularly discerning and disciplined in their stock selection, with a strong focus on fundamentals and quality rather than relying solely on growth narratives or near-term earnings trends. Q) Are we entering another phase where investors are buying anything that is remotely linked to capex, defence, manufacturing, power or AI?
A) This is not just an India-specific phenomenon; globally, companies and sectors linked to the AI supply chain have performed exceptionally well. While India, as a whole, is often not viewed as a major direct beneficiary of the AI revolution, certain segments such as power transmission and distribution, data centres, and related infrastructure have emerged as India's AI play.
As a result, valuations in many of these areas have become quite expensive. Apart from this, the defence sector is witnessing a clear divergence in performance, with private-sector players significantly outperforming public-sector companies.
This is being driven by both the broader indigenisation push and the increasing participation of private companies in the sector. For some of these capital-intensive sectors, it will take time to determine how attractive their long-term returns and economics ultimately prove to be.
However, at the moment, anything associated with these themes continues to perform strongly. Therefore, investors need to be particularly selective and thoughtful about the areas in which they choose to participate.
Read more: Nifty oversold, IT poised for pullback: Anand James on what traders should do nextQ) The IPO pipeline is exploding. Are investors buying businesses or just buying the hope of listing gains?
What is your view on the upcoming NSE IPO? A) It is encouraging for investors when more companies access the equity markets, as it expands the range of business models and management teams available for investment.
Over the last six months, we have witnessed significant activity in the primary market, with a steady pipeline of IPOs across sectors. As with any IPO, different categories of investors tend to have different objectives.
Short-term investors may choose to monetize gains around the time of listing, while long-term investors often use such opportunities to build positions by purchasing shares from those exiting. Within this framework, we believe that most institutional participants, such as mutual funds and insurance companies, typically approach IPO investments with a long-term perspective.
With respect to NSE, we do not comment on individual companies. However, equity exchanges represent a strong and resilient business model that tends to benefit over the long term from economic growth, increasing financialization, and rising participation in capital markets.
As economies grow larger and more investors enter the financial ecosystem, exchanges are generally well positioned to benefit from higher levels of market activity and engagement. Q) If you are sitting on 30-40% gains in mid and smallcaps, what should you do today—hold, trim or rotate?
A) Investments in equities should always be aligned with one’s long-term financial goals. Historically, both mid-cap and small-cap stocks have delivered strong returns over extended periods, and we believe they have the potential to generate healthy returns going forward as well.
There will be inevitably phases when these segments remain range-bound or go through periods of consolidation. However, their long-term track record suggests that patient investors have generally been rewarded over time.
In fact, over the last couple of years, mid and small-cap stocks experienced a similar consolidation phase, but they have recovered strongly over the past six months. Attempting to time such market movements consistently is extremely difficult.
Therefore, investors with a long-term investment horizon should remain invested in fundamentally strong mid and small-cap businesses and stay focused on their financial goals rather than short-term market fluctuations. Over time, this disciplined approach is likely to generate meaningful wealth creation.
Q) Can domestic liquidity permanently offset sustained FII selling, or are we underestimating the influence foreign investors still have on valuations and sentiment? A) Overreliance on foreign investors was a key risk for the Indian market around six to seven years ago, when FII ownership stood at nearly 25% and domestic institutional investors, such as mutual funds and insurance companies, were relatively smaller participants.
Today, however, FII ownership has declined to around 15%, while domestic institutions have grown significantly in scale and influence. As a result, the impact of FII flows on the market is far lower than it used to be.
More over, Indian households remain under-allocated to equities relative to other asset classes. As financialization continues and retail participation in mutual funds grows, we believe domestic flows are likely to remain strong.
Consequently, the relative influence of FII flows on the market should continue to diminish over time. That said, FII flows still play an important role in shaping near-term market sentiment.
However, over the last few years, the Indian market has demonstrated its ability to remain resilient even during periods of sustained foreign outflows, supported by strong domestic participation. Overall, it is a positive development that Indian households and institutions are increasingly owning a larger share of Indian businesses.
This shift not only strengthens the domestic investor base but also makes the market less dependent on foreign capital than it was in the past. Q) The market is now watching the US Fed closely.
How sensitive is India to the possibility that US rates may remain higher for longer? A) Globally, interest rates in developed markets, particularly the US, have a significant influence on the global rate cycle given the interconnected nature of capital flows across countries.
Similar to the US, which is experiencing elevated inflationary pressures due to geopolitical developments, India has also faced inflationary pressures driven by higher crude oil prices and broader commodity inflation. As a result, the inflation and interest rate cycles across markets may move in a similar direction, as several of the underlying drivers are common.
Consequently, if interest rates continue to rise, one could see some moderation in economic growth as higher borrowing costs begin to weigh on consumption and investment. That said, these concerns could ease considerably if the conflict in West Asia de-escalates and crude oil as well as other commodity prices revert closer to their historical ranges.
Such a development would help alleviate inflationary pressures, reduce the need for further monetary tightening, and provide greater support to economic growth. Q) US Treasury yields have been moving higher, and historically rising yields tend to trigger a risk-off sentiment by making safe US assets more attractive and tightening global liquidity.
How serious a risk is this for Indian equities, particularly expensive mid and smallcaps? A) Yes, there is a saying that when the US sneezes, the rest of the world catches a cold.
Therefore, there is always a risk that higher interest rates in the US could dampen global risk appetite and lead to greater market volatility. However, as discussed earlier, the influence of foreign investors on the Indian market has gradually declined over the years, while domestic retail and institutional participation has increased significantly.
As a result, the potential impact of foreign capital flows on the broader market is more limited today than it was in the past. That said, irrespective of foreign investor activity, the current market environment warrants a disciplined and selective investment approach.
Investors need to be particularly mindful of the valuations they are paying for individual companies. Over shorter time horizons, market corrections often tend to be sharper in expensive stocks and sectors that have previously enjoyed strong investor enthusiasm and substantial valuation expansion.
Therefore, while external factors such as US interest rates remain relevant, the more important consideration for investors today is maintaining valuation discipline and focusing on businesses with strong fundamentals and reasonable expectations embedded in their stock prices.
Pre-orders for the new iPhone Duo don’t start until later in October, but the device may already have its first killer app. Or at least its most whimsical one!...